Bankruptcy, Chapter 7
Chapter 7 Bankruptcy In Minneapolis, MN
Chapter 7 is the part of the Bankruptcy Code, 11 U.S.C. §§ 701 to 784, that discharges, or wipes out, many unsecured debts such as credit cards, medical bills and personal loans, usually within a few months of filing. It is sometimes called liquidation, because a trustee may sell property that is not protected by an exemption, but in many consumer cases everything the person owns is covered by the exemptions and nothing is sold.
How It Works
What Is Chapter 7Bankruptcy?
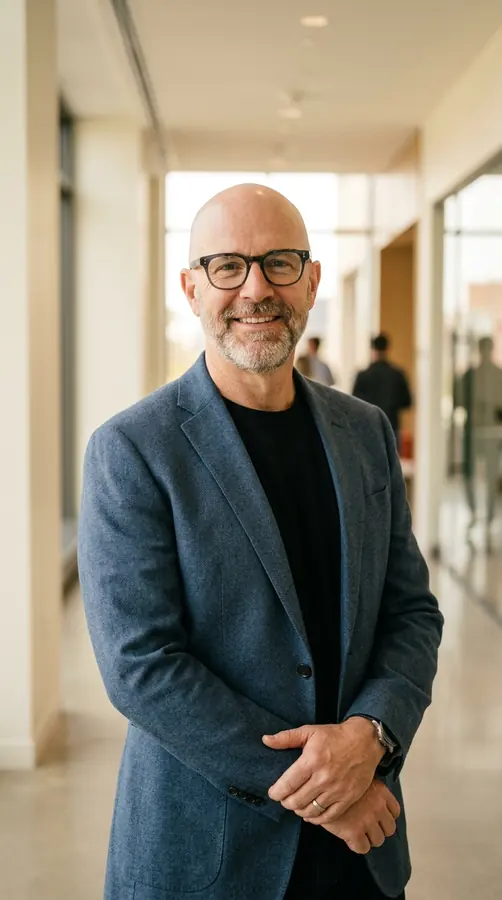
Whitlock Reyes LLP handles Chapter 7 cases from its Minneapolis office for people across the Twin Cities. You speak with the partner who will file your case, and the first consultation is free.
Tobias Reyes
Name Partner, Whitlock Reyes LLP
Practice Areas
Who It Is For
Who Is Chapter 7For?
Related pages
Chapter 7 is generally for people who cannot realistically pay their debts from their income. It is often a fit in one of these situations.
Debt has outgrown income
Credit cards, medical bills or personal loans you cannot pay down from what you earn.
Little property, or exempt property
What you own is modest, or it is protected by the exemptions you can claim.
Foreclosure or repossession is coming
The automatic stay can pause these while the case is open, which buys time to decide.
You want the quicker route
Chapter 7 usually finishes far sooner than a three to five year Chapter 13 plan.
Garnishment or lawsuits
Creditors are threatening to garnish wages or have already filed suit.
Step By Step
How Does A Chapter 7Case Work Here?
Credit counseling
A short course from an approved agency, completed within the 180 days before filing.
Petition and schedules
Your property, debts, income and expenses are filed with the court, with the exemptions you claim.
The automatic stay
Collection calls, garnishments and most lawsuits pause as soon as the case is filed.
Meeting with the trustee
About a month later, the trustee asks questions under oath about your paperwork. Creditors rarely attend.
Debtor education
A second short course on personal finances, completed before the discharge can be entered.
Discharge
After the objection deadline passes, the court issues an Order of Discharge for the debts that qualify.
Case Notes
Chapter 7,Written Up Plainly.
Which debts survive a Chapter 7?
Some debts usually survive a discharge under 11 U.S.C. § 523: most student loans, recent income taxes, child support and spousal maintenance, debts from fraud, and fines owed to the government. A secured lender also keeps its lien, so a car or house you no longer pay for can still be taken back.
Put everything on the table, including the things you are worried about. A court can deny a discharge if assets are hidden, if a debtor does not cooperate with the trustee, or if creditors are defrauded.
Chapter 7 or Chapter 13?
Chapter 7 is faster and usually simpler. Chapter 13 takes three to five years but can save a house that is behind on payments, protect property that Chapter 7 would not, and handle some debts that Chapter 7 cannot. If your income is above the median, or you are behind on a mortgage you want to keep, Chapter 13 may be the better fit, and the bankruptcy page explains how a Chapter 13 plan works.
In Detail
Chapter 7,Question By Question.
Do you qualify? The means test
Every Chapter 7 case starts with the means test in 11 U.S.C. § 707(b). It compares your household income over the six months before filing to the median income for a household of your size in your state. If you are under the median, you generally qualify. If you are over it, a second calculation subtracts allowed living expenses and certain debt payments to see whether you could fund a Chapter 13 plan instead.
The test is mechanical, but the inputs are not always obvious: irregular income, a recent job loss, business income and household size all change the result. We run those numbers with you before anything is filed, so you know the answer before the court does.
What can you keep in a Chapter 7?
Exemptions decide what you keep. Depending on the state, a filer uses the state's own list or chooses between the state list and the federal list, and each protects some equity in a home, a vehicle up to a set value, household goods, qualifying retirement accounts and certain insurance and public benefits. The limits are dollar figures that change over time, so they are checked against your own property rather than assumed.
If you are current on a car loan or mortgage and want to keep the property, you can usually keep paying it, sometimes by signing a reaffirmation agreement. Choosing the right exemptions is one of the decisions that matters most, and it is made with you, line by line.
What should you bring?
Recent pay stubs, your last two tax returns, recent bank statements, your bills and collection letters, any lawsuit or garnishment papers, your vehicle and mortgage statements, and a list of what you own.
Questions
Questions AboutChapter 7.
When to call us
You call, and the first conversation tells you whether Chapter 7 fits, or whether Chapter 13, an alternative to bankruptcy, or no filing at all makes more sense. If Chapter 7 is the route, you leave with a list of what to gather, the credit counseling course to complete before filing, and a plain timeline from filing to discharge.
We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code.
(555) 014-2200How do I know if I pass the means test?
The means test compares your household income to the median for a household of your size in your state. If you are under it, you generally qualify; if you are over it, a second calculation using your expenses decides. We run the numbers with you at the start.
Will I keep my car and my home?
Many people do. Exemptions can protect some home equity and personal property, and a car loan that is current can often be kept. It depends on your equity, your loans and your exemptions, which is why the numbers come first.
How long does a Chapter 7 case take?
Many Chapter 7 cases reach a discharge within a few months of filing. A case can take longer if the trustee has questions or there are assets to administer.
Which debts does Chapter 7 not wipe out?
Some debts usually survive, such as most student loans, recent taxes, child support and spousal maintenance. Which of your debts qualify is part of the first conversation.
What happens to my tax refund?
A refund you are owed when you file can become part of the case, so the timing of the filing and how the refund is used are planned in advance.
Can I file Chapter 7 if I filed before?
A new Chapter 7 discharge is generally not available within eight years of a previous Chapter 7 filing. Other waiting periods apply to Chapter 13, so your filing history is checked at the start.
Free Consultation
Tell Us What Is Going On.The First Call Is Free.
- A plain answer on the first call
- You speak with a partner, not an intake line
- Open weekdays, 8:00 to 6:00, or leave a message
 Marguerite Whitlock