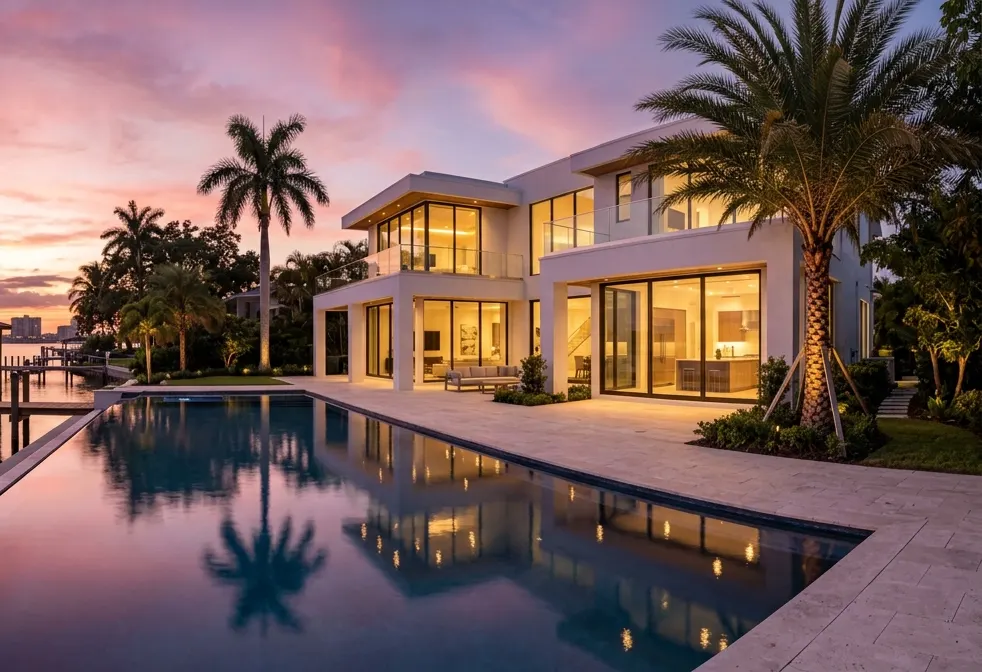
The view sells the house. The seawall, elevation and insurance decide the deal.
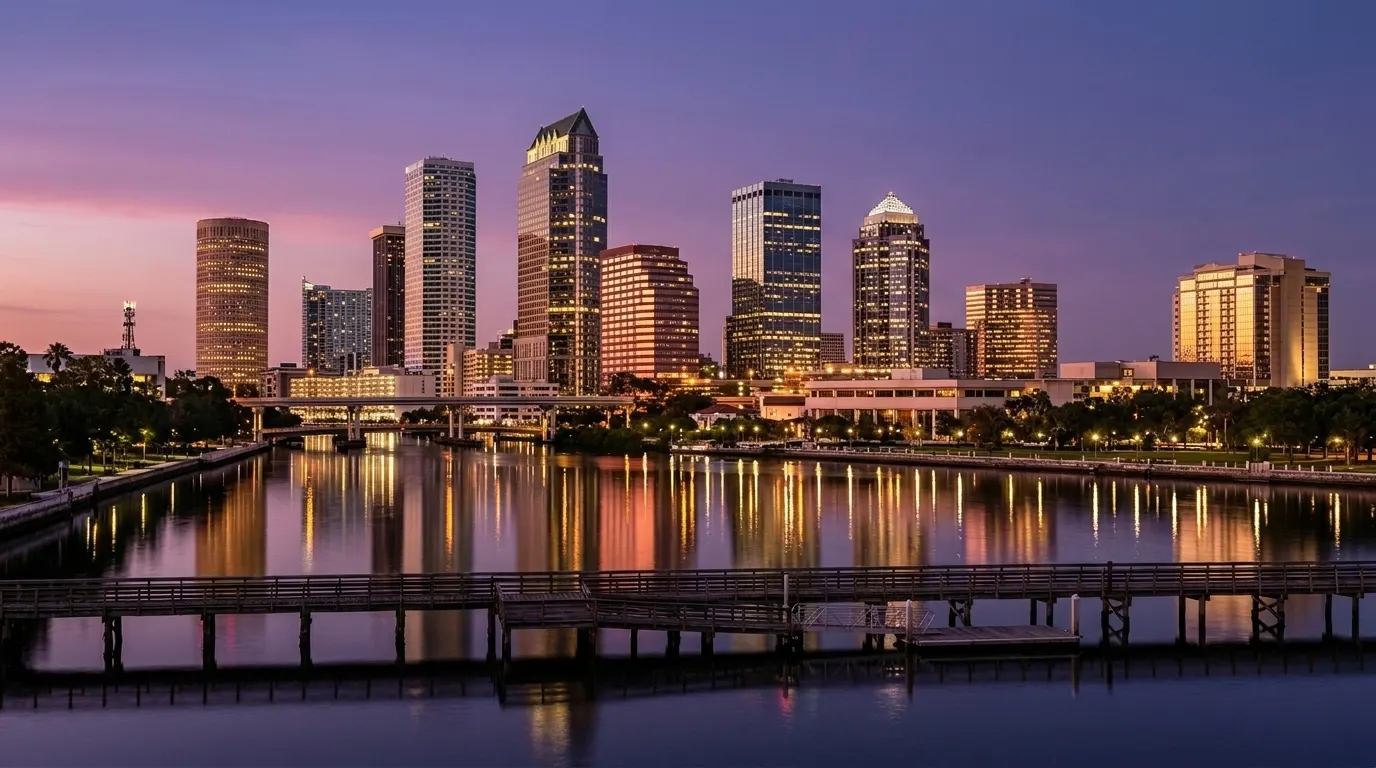
Tampa has more waterfront than most people expect: deep-water lots on Davis Islands and Harbour Island, the high-rises along Bayshore Boulevard, canal homes in Sunset Park and Culbreath Isles, and quiet lakes in Carrollwood and Lutz. Each kind of water brings its own questions about access, maintenance and cost.
We have bought and sold homes on every one of them. That means we ask for the seawall survey and the elevation certificate before the first showing, get flood and wind insurance quotes during the search rather than after the contract, and know which bridges a sailboat mast will clear on the way to the bay.
For sellers, waterfront marketing starts on the water. We photograph from the dock and, where it helps, from a boat at the hour the light is kindest, and we put the survey, permits and insurance history in the disclosure package so serious buyers can move quickly.
What sets a waterfront price in Tampa
Two homes on the same island can be worlds apart in value. These are the factors we weigh first.
Water depth and access
Deep water with no fixed bridges is worth more to boaters than a shallow canal behind a low span.
View line and exposure
Open bay views and sunset exposure command a premium over canal or lake views.
Elevation and flood history
A raised first floor and a clean claims history lower insurance costs and widen the pool of buyers.
Seawall and dock condition
A recent seawall cap or dock rebuild can be worth tens of thousands in a buyer's eyes.
Insurance on the water: plan for it early
Insurance is one of the largest costs of owning a waterfront home in Tampa, and it can vary widely between two houses on the same street. Elevation, the age and shape of the roof, wind protection on windows and doors, and past claims all move the premium.
That is why we request the elevation certificate and claims history before you tour, and why we suggest calling an insurance agent during the search rather than after a contract is signed. A quote in hand turns a beautiful house into a monthly number you can judge.
Some owners lower their costs over time with roof upgrades, impact windows or a wind mitigation inspection. We can introduce contractors and inspectors, though the decision and the savings depend on your insurer and your home.
Insurance also shapes your resale. A home with a raised first floor, a newer roof and documented wind protection is easier for the next buyer to insure, which widens the pool of people who can buy it and supports the price when it is your turn to sell. We keep that in mind when you compare homes now.
Seawalls, docks and lifts: what we ask for
Before you write an offer on a waterfront home, these documents should be in hand.
A marine contractor's notes on cracks, cap condition and tiebacks, ideally from the past two years.
Confirmation that the dock, lift and any boathouse were permitted and closed out with the county or city.
Quotes based on the home's elevation certificate, so the monthly cost is known before the inspection period ends.
Any past flood or wind claims, repairs made and whether the home took water in recent storms.
Condos and high-rises on the water
Not every waterfront buyer wants a seawall to look after. The towers along Bayshore Boulevard, Harbour Island and the downtown riverfront offer bay and river views with the building handling the outside maintenance. In exchange, you share the building's costs and decisions with your neighbors.
That makes the association as important as the unit. We collect the budget, the reserve study, recent inspection reports and the minutes of the last several board meetings. Together they show whether the building is setting enough aside for its roof, elevators and structure, and whether a special assessment is on the horizon. Florida has added inspection and reserve requirements for many condominium buildings in recent years, so ask the association where your building stands.
We also look at the details that shape daily life: parking and storage, rules on pets and leasing, guest policies and how the building handled its most recent storm season. A unit with a fine view in a well-run building is usually a better purchase than a slightly larger one in a building with deferred work.
Buying on the water, step by step
The usual purchase steps, with a few added for homes on the water.
Bay, canal or lake; boat size and mast height; how far you will travel to open water.
We request surveys, elevation certificates and insurance history before you tour.
A home inspection, a seawall inspection and, for larger docks, a marine contractor's look.
Flood and wind policies bound before closing, with the lender's requirements met.
Selling a waterfront home
Waterfront buyers do a lot of homework before they call, so the listing has to answer their questions up front. We gather the seawall report, dock permits, elevation certificate and insurance history and make them available to serious buyers from the first week.
Presentation matters on the water. We photograph from the dock and, where it helps, from a boat, at the hour the light suits the view. A short video that shows the route to open water or the sunset line can do more than a dozen still photos.
Pricing follows the factors that set waterfront value: water depth and access, the view line, elevation and the condition of the seawall and dock. Your written pricing memo explains each one and shows the closed sales we used, so you can see how the range was reached.
Waterfront, asked and answered
Short answers for buyers and owners on the water. An insurance agent can quote your own home. See also Buying a home, Selling your home and a waterfront listing.